What is the market overview and scope of the Copper Wire Market?
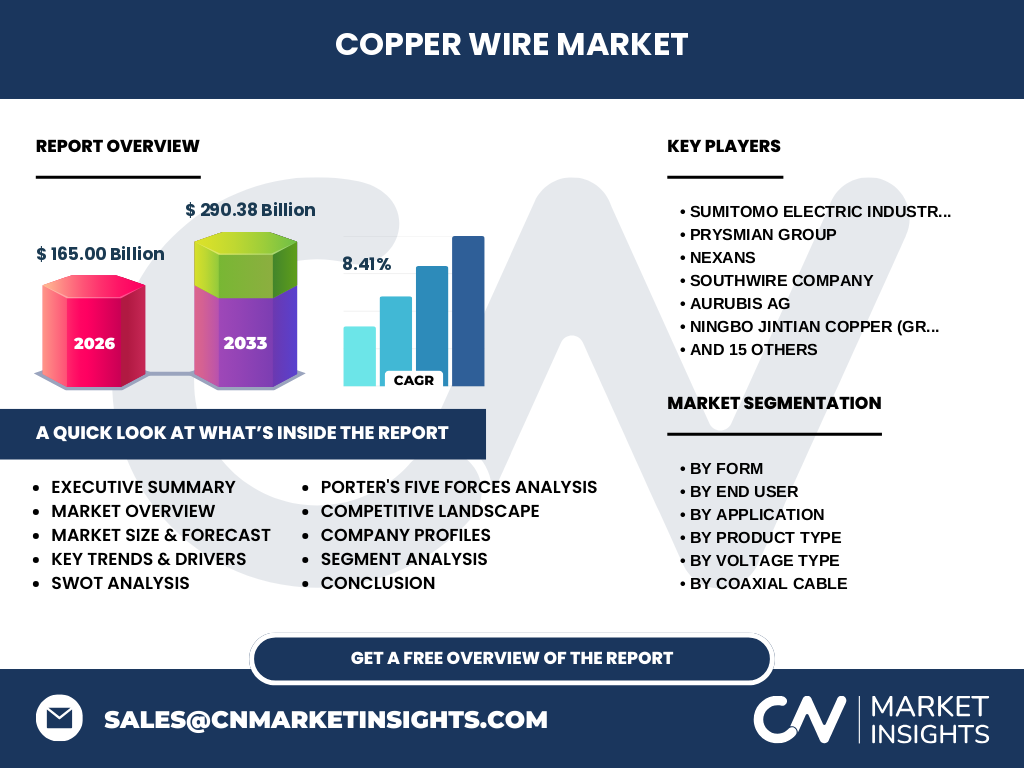
The Copper Wire Market represents a critical backbone for global electrification, valued at 165.00 Billion in 2026. Our analysis indicates that raw material cathode inputs and strict electrical standards govern this sector, which spans solid and stranded configurations utilized across residential, commercial, and heavy industrial electrical grids.
Key market drivers, restraints, challenges, and opportunities shaping the Copper Wire Market
Structural growth is heavily propelled by renewable energy integration and electric vehicle adoption, though volatile LME copper pricing acts as a primary market constraint. Industry participants face severe logistical hurdles in raw material procurement, opening lucrative strategic opportunities in high-voltage transmission upgrades.
Emerging trends and growth patterns in the Copper Wire Market
The shift toward lightweight, high-conductivity magnet wire and advanced twisted pair cable configurations is accelerating. Industry trends highlight a major pivot toward sustainable manufacturing processes among leading producers to meet tightening international environmental compliance mandates.
How did COVID-19 impact the Copper Wire Market and its recovery trajectory?
Pandemic-induced supply chain disruptions severely constrained copper cathode processing operations globally. Recovery trajectories rebounded sharply as government-backed infrastructure stimulus packages unlocked delayed capital expenditure for power distribution networks and grid modernization.
Competitive Benchmarking and Market Concentration
The competitive landscape features high market concentration among Tier-1 multinational cable manufacturers. Strategic dynamics rely on vertical integration, where giants like Prysmian Group and Nexans leverage proprietary compounding technologies to maintain pricing power over regional competitors.
Executive Summary of the Copper Wire Market
Our comprehensive research projects the Copper Wire Market to expand from 165.00 Billion in 2026 to reach 290.38 Billion by 2033, registering a robust 8.41% CAGR. This expansion is underpinned by relentless urbanization and the global energy transition.
Market Forecast and Long-Term Projections (2027 to 2033)
Driven by aggressive grid decarbonization targets, the market will scale from 165.00 Billion in 2026 to 290.38 Billion by 2033 at an 8.41% CAGR. This trajectory rewards firms investing in high-voltage direct current infrastructure and advanced subsea cabling solutions.
Segmentation Analysis of the Copper Wire Industry
Market segmentation spans multiple parameters: forms include solid and stranded wire; end users range from residential to industrial sectors; and applications cover building wire, automotive, and renewable energy. Specialized product types like coaxial, twisted pair, and multi-conductor cables cater to nuanced telecommunications and industrial automation requirements.
Geographic distribution and regional performance dynamics
Regional performance varies widely, with Asia-Pacific dominating consumption due to rapid industrialization and massive urban sprawl. Meanwhile, North America and Europe focus heavily on replacing aging grid infrastructure and integrating offshore wind energy transmission corridors.
In-Depth Regional Review and Localized Constraints
Localized constraints in developing regions include stringent import tariffs on refined copper and inadequate port logistics for heavy drum transport. Conversely, advanced economies enforce strict regulatory compliance regarding fire-retardant cable sheathing and energy efficiency standards.
Company Profiles and Strategic Positioning
Market leaders such as Sumitomo Electric Industries, Southwire Company, and Aurubis AG leverage massive smelting capacities and global distribution networks. Their strategic positioning focuses on securing long-term mining off-take agreements to insulate margins against raw material volatility.
Porter's Five Forces Analysis for Copper Wire Production
Bargaining power of suppliers remains high due to the oligopolistic nature of copper mining, whereas buyer power is moderate given the commoditized nature of standard building wire. Threat of substitutes is remarkably low due to copper's unmatched thermal and electrical conductivity.
SWOT Analysis of the Copper Wire Sector
Core strengths include exceptional conductivity and established recycling loops, countered by weaknesses in exposure to LME price swings. Opportunities thrive in EV wiring harnesses, while threats stem from geopolitical trade disputes affecting cathode supply chains.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with copper mining and smelting by firms like KGHM and Freeport, progressing through continuous rod casting, wire drawing, and insulation extrusion. Downstream value is captured by electrical contractors and OEMs integrating these wires into finished industrial machinery.
Investment Insights and High-Potential Areas
High-potential investment pockets concentrate on specialized magnet wire for electric vehicle traction motors and high-voltage subsea cables for offshore wind farms. Investors should prioritize manufacturers with secured green-metal supply chains to mitigate future carbon tax liabilities.
Conclusion and Key Strategic Takeaways
The Copper Wire Market offers compelling growth, projected to hit 290.38 Billion by 2033. Success in this landscape demands operational agility, rigorous raw material hedging, and alignment with clean energy mega-trends.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry export data, primary stakeholder interviews with chief procurement officers, and macroeconomic industrial production indices. This multi-tiered approach ensures maximum forecast accuracy for the Copper Wire Market industry trends.
Scope of the Report and Coverage Parameters
This report evaluates the global Copper Wire Market analysis across all major voltage classes, product categories, and geographic regions from 2026 through 2033. Exclusions apply to aluminum-dominant overhead conductors outside designated hybrid system parameters.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum is defined by strategic joint ventures among major players like Prysmian and Nexans aimed at expanding ultra-high-voltage manufacturing plants. Product launches heavily feature eco-friendly, halogen-free building wires designed to meet stringent European construction regulations.